

Company car drivers face a future increase in Benefit-in-Kind (BiK) tax following confirmation in the Autumn Budget that company car tax bands will rise by one percentage point in the 2030/31 tax year.
The change is forecast to raise an additional £310 million for the Treasury in 2030/31, increasing to £345 million in 2031/32.
BiK tax is paid by employees who receive a company car for private use, with the amount determined by factors including the vehicle’s taxable list price and its applicable tax band. The change means businesses and drivers will need to consider the longer-term tax implications when selecting vehicles and agreeing lease terms.
We've laid out a table outlining the current BiK percentages followed by the increases for the 2030/31 tax year.
|
CO₂ emissions |
Electric range |
2026/27 |
2027/28 |
2028/29 |
2029/30 |
2030/31 |
|---|---|---|---|---|---|---|
|
0 |
Fully electric |
4% |
5% |
7% |
9% |
10% |
|
1–50 |
Over 130 miles |
4% |
5% |
18% |
19% |
20% |
|
1–50 |
70–129 miles |
7% |
8% |
18% |
19% |
20% |
|
1–50 |
40–69 miles |
11% |
12% |
18% |
19% |
20% |
|
1–50 |
30–39 miles |
13% |
14% |
18% |
19% |
20% |
|
1–50 |
Under 30 miles |
15% |
16% |
18% |
19% |
20% |
|
51–54 |
Not applicable |
16% |
17% |
18% |
19% |
20% |
|
55–59 |
Not applicable |
17% |
18% |
19% |
20% |
21% |
|
60–64 |
Not applicable |
18% |
19% |
20% |
21% |
22% |
|
65–69 |
Not applicable |
19% |
20% |
21% |
22% |
23% |
|
70–74 |
Not applicable |
20% |
20% |
21% |
22% |
23% |
|
75–79 |
Not applicable |
20% |
20% |
21% |
22% |
23% |
|
80–84 |
Not applicable |
21% |
21% |
22% |
23% |
24% |
|
85–89 |
Not applicable |
22% |
22% |
23% |
24% |
25% |
|
90–94 |
Not applicable |
23% |
23% |
24% |
25% |
26% |
|
95–99 |
Not applicable |
24% |
24% |
25% |
26% |
27% |
|
100–104 |
Not applicable |
25% |
25% |
26% |
27% |
28% |
|
105–109 |
Not applicable |
26% |
26% |
27% |
28% |
29% |
|
110–114 |
Not applicable |
27% |
27% |
28% |
29% |
30% |
|
115–119 |
Not applicable |
28% |
28% |
29% |
30% |
31% |
|
120–124 |
Not applicable |
29% |
29% |
30% |
31% |
32% |
|
125–129 |
Not applicable |
30% |
30% |
31% |
32% |
33% |
|
130–134 |
Not applicable |
31% |
31% |
32% |
33% |
34% |
|
135–139 |
Not applicable |
32% |
32% |
33% |
34% |
35% |
|
140–144 |
Not applicable |
33% |
33% |
34% |
35% |
36% |
|
145–149 |
Not applicable |
34% |
34% |
35% |
36% |
37% |
|
150–154 |
Not applicable |
35% |
35% |
36% |
37% |
38% |
|
155–159 |
Not applicable |
36% |
36% |
37% |
38% |
39% |
|
160+ |
Not applicable |
37% |
37% |
38% |
39% |
40% |
Electric cars have benefited from comparatively low BiK rates, helping make them attractive through company car and salary-sacrifice schemes. Any future rate changes could therefore influence the overall cost of these arrangements.
Fleet managers should factor the confirmed changes into whole-life cost calculations and employee communications, while checking the applicable rates for each vehicle and tax year.
Similar Stories
EV pay-per-mile tax remains on track for April 2028
Electric vehicle drivers are still set to face a new mileage-based tax from A...
Toyota’s electric-van growth shows established LCV brands are gaining momentum
Toyota’s latest European sales results show electric commercial vehicles gain...
Fuel inflation makes efficiency measures more valuable again
Rising fuel prices are putting fresh pressure on fleets still operating signi...
Public Charging Price Watch: 55p charging now comes with rewards too
This week’s Price Watch shows how public charging value is increasingly movin...
UK fleet managers still expect an electric future despite policy uncertainty
Confidence in long-term electrification remains high among UK fleet managers ...
Business mileage rates rise as Budget delivers relief for drivers
Employees using their own cars for business travel will benefit from more gen...
£100m Budget fund aims to cut costs at local EV chargers
The Government has announced £100 million of funding to reduce prices at loca...
Autumn Budget 2026: VAT reduction on household electricity extended until July 2027
Electric vehicle drivers who charge at home are set to benefit from an extens...
Autumn Budget 2026: the fleet industry responds
The Autumn Budget 2026 has delivered a mixed package for the fleet industry, ...
The Autumn Budget 2026: What fleet operators need to know
The Autumn Budget brings a mixed outlook for fleet operators and company car ...
Autumn budget: 5p fuel duty cut extended to July 2027
Fleet operators and drivers have been given further relief after the Chancell...
Chery unveils new TIGGO 7 and TIGGO X7 SUVs
Chery is preparing to expand its UK SUV line-up with the TIGGO X7, a new, mor...
Uncertainty over BiK rates delays salary sacrifice decisions
Uncertainty over future Benefit-in-Kind (BiK) tax rates is prompting drivers ...
Volvo EX60 production ramp-up delayed as model receives 50,000 orders
Fleets may have to wait longer than anticipated if operators have ordered the...
Changan introduces S05 PHEV to UK market
Chinese car manufacturer, Changan has introduced its first hybrid vehicle to ...
Better Fleet: Make the business case survive the contract
One of the weaknesses in traditional fleet procurement: A supplier may delive...
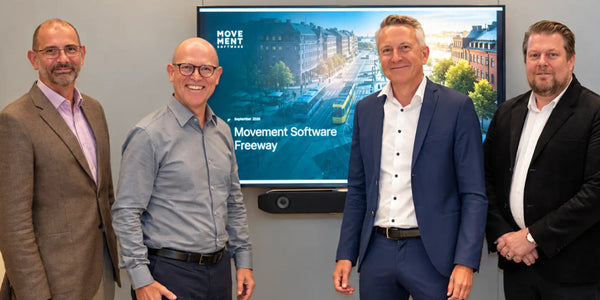
Fleet software consolidation continues as Freeway joins Movement Software
Movement Software has acquired UK fleet-maintenance specialist Freeway Fleet ...
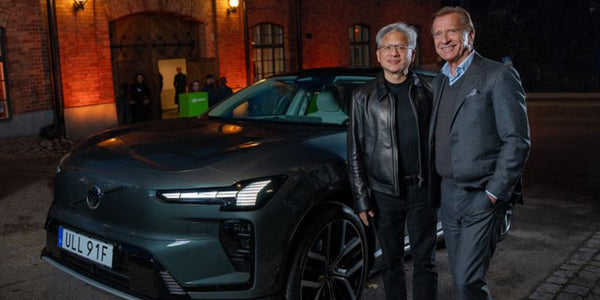
Software-defined safety will change how fleets buy vehicles
Volvo Cars is expanding its partnership with NVIDIA to develop future automat...
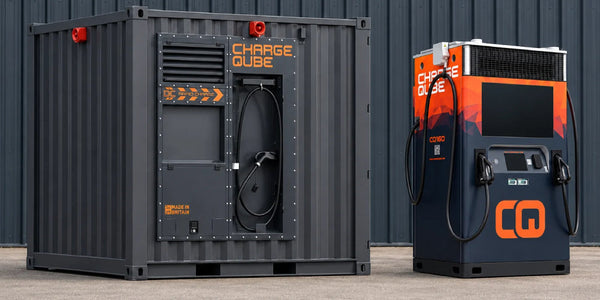
Mobile battery charging could keep EV plans moving through grid delays
Fleet electrification projects do not always stall because the vehicles are u...
Government unveils tougher rules on private parking charges
Drivers will receive greater protection against unfair private parking charge...
Government targets clocking with tougher action against used car dealers
The UK Government is proposing tougher action against used-car dealers that m...
OMODA 4 compact SUV confirmed for UK launch in 2027
Omoda has confirmed its new compact SUV, the Omoda 4, will be available to UK...
iCAUR confirms V27 SUV for UK launch in 2027
Chinese automotive brand iCAUR will make its UK debut in early 2027, with the...
Updated Mazda CX-30 brings new trim and subtle tweaks
Mazda has unveiled its updated 2027 CX-30, with a wider model range, revised ...
Van tool theft costs UK businesses £1.7bn as fleets face costly downtime
Tool theft is causing significant disruption for UK van fleets, with one in f...
Toyota calls for greater flexibility in UK and EU emissions regulations
Toyota has called for more flexible vehicle emissions regulations in the UK a...